Charts / Chart
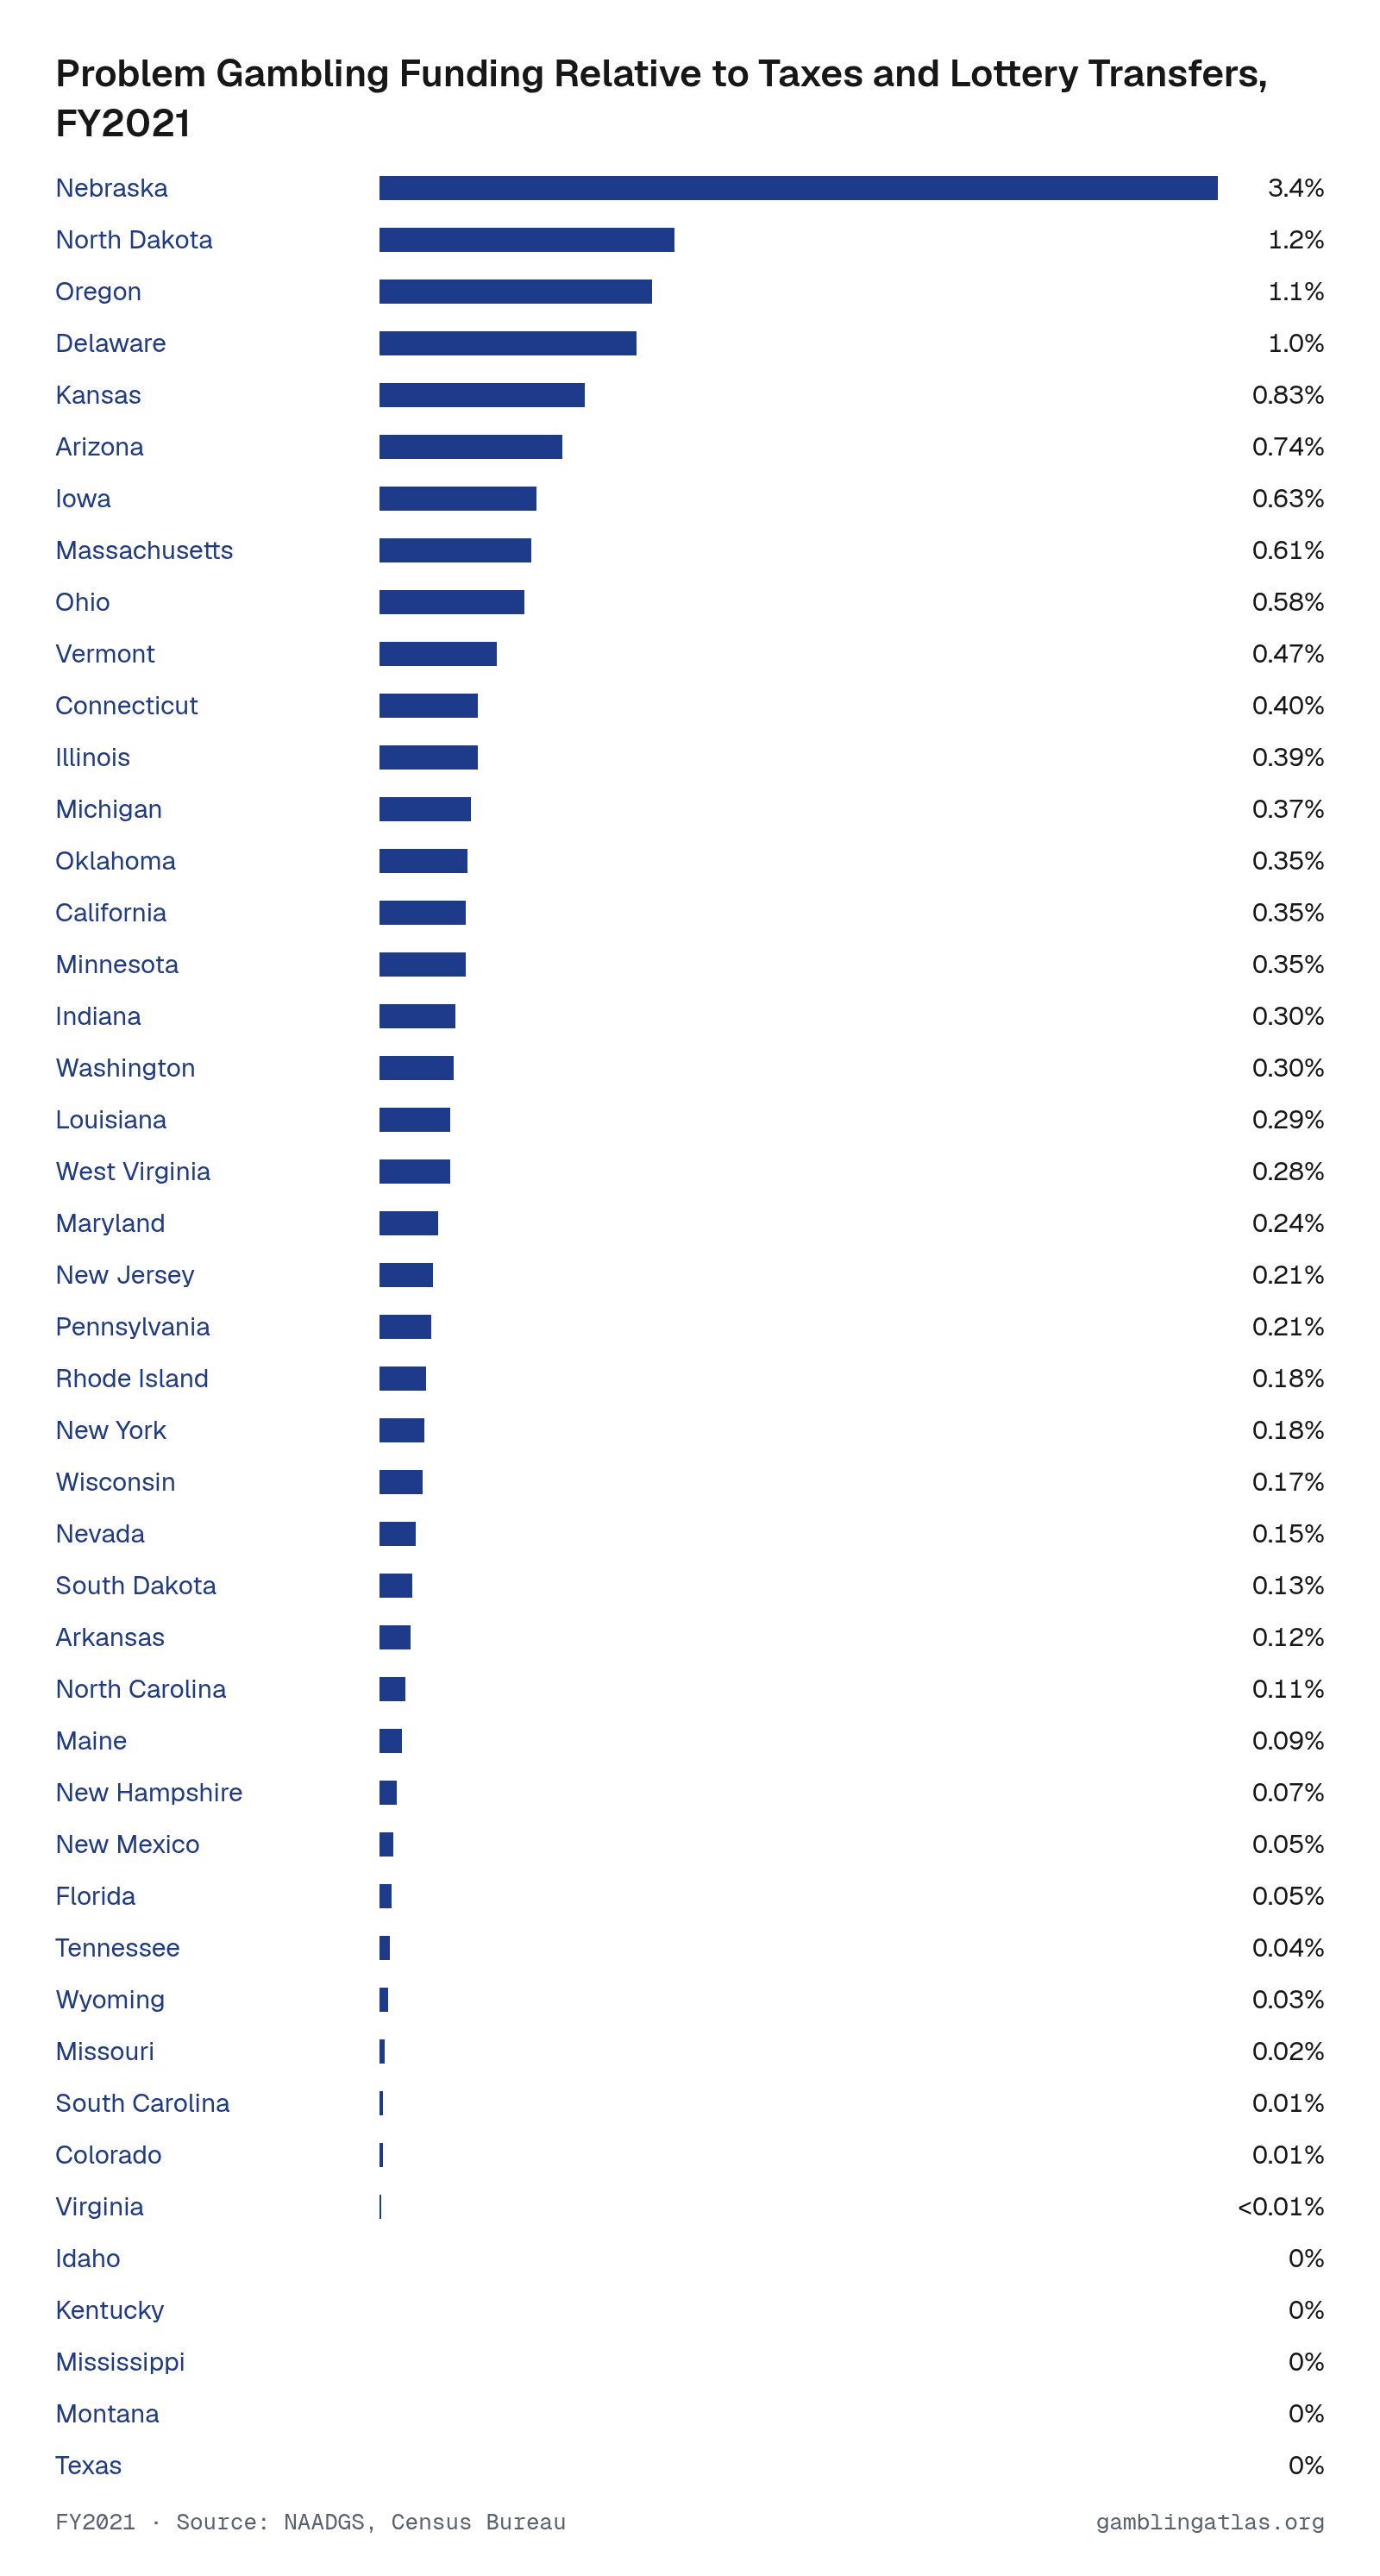
Problem Gambling Funding Relative to Taxes and Lottery Transfers, FY2021
In FY2021, public problem-gambling funding in the 45 states shown equaled 0.26% of their gambling and amusement taxes and lottery proceeds. Nebraska had the largest ratio (3.37%).
State fiscal years end on different dates. This FY2021 comparison does not measure whether online sports betting launches changed funding.
Alaska, Alabama, District of Columbia, Georgia, Hawaii and Utah have missing figures or collected less than $20 million and are left out.
FY2021 · Source: NAADGS, Census Bureau · Problem gambling
Download, embed or cite
Free to reuse with a link to this page. License and sources
Data
| State | Funding | Gambling and amusement taxes and lottery proceeds | Share |
|---|---|---|---|
| Nebraska | $1.9M | $54.9M | 3.37% |
| North Dakota | $360K | $30.4M | 1.18% |
| Oregon | $7.0M | $641M | 1.10% |
| Delaware | $1.4M | $135M | 1.03% |
| Kansas | $712K | $86.1M | 0.83% |
| Arizona | $2.3M | $318M | 0.74% |
| Iowa | $3.0M | $473M | 0.63% |
| Massachusetts | $10.2M | $1.68B | 0.61% |
| Ohio | $6.3M | $1.08B | 0.58% |
| Vermont | $150K | $31.9M | 0.47% |
| Connecticut | $2.6M | $659M | 0.40% |
| Illinois | $6.8M | $1.73B | 0.39% |
| Michigan | $5.5M | $1.50B | 0.37% |
| Oklahoma | $1.0M | $283M | 0.35% |
| California | $8.7M | $2.50B | 0.35% |
| Minnesota | $1.1M | $329M | 0.35% |
| Indiana | $3.0M | $1.01B | 0.30% |
| Washington | $730K | $242M | 0.30% |
| Louisiana | $2.6M | $900M | 0.29% |
| West Virginia | $1.5M | $512M | 0.28% |
| Maryland | $4.1M | $1.74B | 0.24% |
| New Jersey | $3.1M | $1.48B | 0.21% |
| Pennsylvania | $6.4M | $3.06B | 0.21% |
| Rhode Island | $550K | $297M | 0.18% |
| New York | $5.6M | $3.03B | 0.18% |
| Wisconsin | $396K | $230M | 0.17% |
| Nevada | $1.3M | $843M | 0.15% |
| South Dakota | $244K | $182M | 0.13% |
| Arkansas | $220K | $176M | 0.12% |
| North Carolina | $1.0M | $936M | 0.11% |
| Maine | $106K | $114M | 0.09% |
| New Hampshire | $100K | $140M | 0.07% |
| New Mexico | $70.0K | $129M | 0.05% |
| Florida | $1.3M | $2.41B | 0.05% |
| Tennessee | $200K | $521M | 0.04% |
| Wyoming | $7,188 | $22.1M | 0.03% |
| Missouri | $154K | $733M | 0.02% |
| South Carolina | $100K | $671M | 0.01% |
| Colorado | $30.0K | $284M | 0.01% |
| Virginia | $55.0K | $778M | 0.01% |
| Idaho | $0 | $74.3M | 0.00% |
| Kentucky | $0 | $388M | 0.00% |
| Mississippi | $0 | $344M | 0.00% |
| Montana | $0 | $131M | 0.00% |
| Texas | $0 | $2.02B | 0.00% |
Notes
The Census tax denominator includes non-gambling amusement businesses and admissions. It excludes tribal payments; lottery transfers are added separately. Missing tax totals are excluded. This is a comparison of totals, not evidence that the funding came from these receipts.
Sources
- 2021 Survey of Publicly Funded Problem Gambling Services in the United States
- Problem Gambling Annual Reconciliation, State Fiscal Year 2021